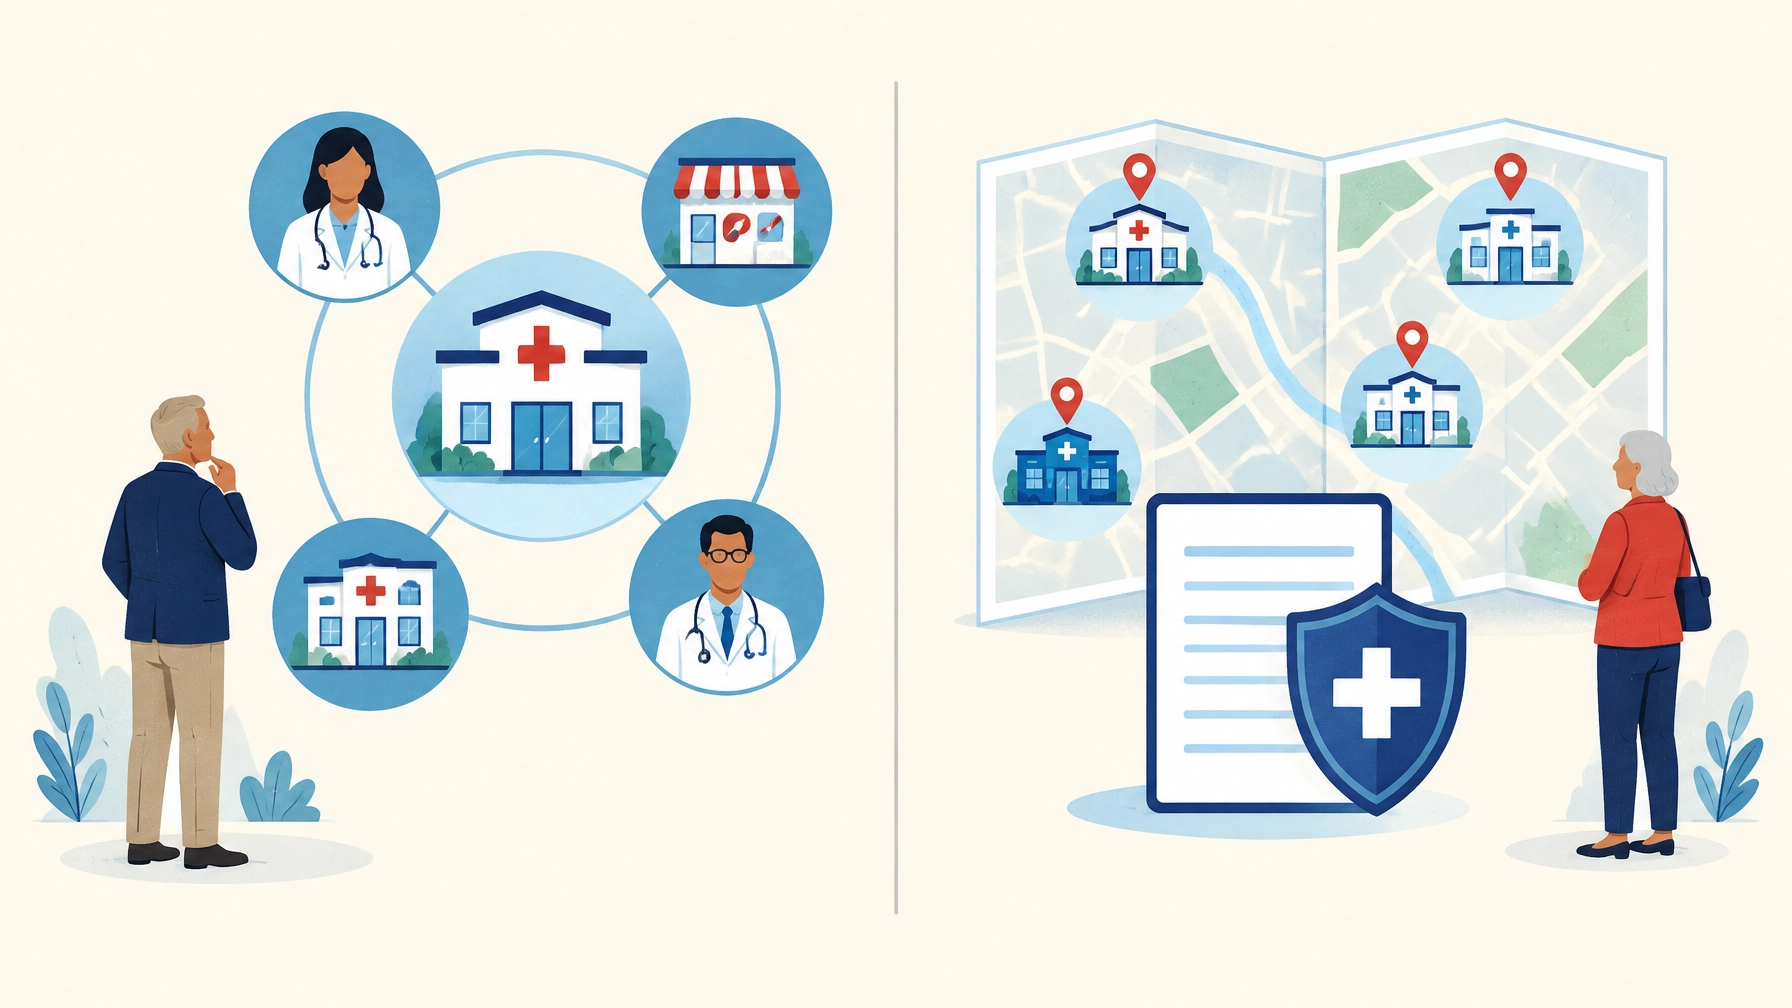
When comparing Medicare Advantage vs. supplement coverage, you’re choosing between two different ways to receive Medicare coverage, not two policies you can use together.
Medicare Advantage is an alternative way to receive your Medicare Part A and Part B benefits through a Medicare-approved private plan. A Medicare Supplement policy, also called Medigap, works alongside Original Medicare to help pay some out-of-pocket costs.
Neither option is the right fit for everyone. Understanding how each works, and considering your doctors, prescriptions, budget, and enrollment timing, can help you make a more informed choice.
The main difference
With Medicare Advantage, you receive Part A and Part B coverage through a private plan. Plans have their own coverage rules and may use provider networks. Most include Part D prescription drug coverage, but details vary by plan.
With Original Medicare and Medigap, Original Medicare remains your primary coverage. You buy a separate Medicare Supplement policy to help cover certain out-of-pocket costs, such as deductibles, copayments, or coinsurance, depending on the policy. You generally need separate Part D coverage if you want Medicare prescription drug coverage.
You can’t have Medigap while enrolled in Medicare Advantage. The two options are different coverage paths.
How Medicare Advantage works
Medicare Advantage plans, also called Part C, are offered by private companies approved by Medicare. You need both Medicare Part A and Part B to join, and you continue paying your Part B premium.
Plan rules vary. Depending on the type of plan, you may need to use a provider network, choose a primary care provider, or get approval before certain services. Most Medicare Advantage plans include Part D, but you should confirm drug coverage for any plan you are considering.
Before enrolling, check:
- Whether your doctors, specialists, hospitals, and pharmacies are included.
- Whether your prescriptions are covered and what plan rules apply.
- What you may pay when you receive care, including deductibles and copayments.
- The plan’s annual out-of-pocket limit for covered medical services.
- Whether referrals or prior authorization may be required.
Plan details can change from year to year. Review current materials carefully rather than assuming a plan’s network, drug coverage, or costs will stay the same.
How Medicare Supplement coverage works
A Medicare Supplement policy is private insurance that works with Original Medicare. It can help pay certain out-of-pocket costs left by Original Medicare, according to the policy’s benefits.
With Original Medicare, you can generally see any provider in the United States that accepts Medicare. There is no Medicare Advantage plan network, though it is still sensible to confirm that a provider accepts Medicare before receiving care.
Medigap policies do not include prescription drug coverage. If you choose Original Medicare with Medigap and want Medicare drug coverage, you generally enroll in a separate Part D plan.
When comparing this route, consider the combined cost of your Part B premium, Medigap policy, Part D plan, and any remaining cost-sharing. A Medigap policy can help with certain expenses, but it does not cover every possible health care cost.
A practical way to compare
Rather than starting with a plan’s advertised features, begin with your own needs.
- Write down your doctors and preferred hospitals. Check whether they accept Medicare and, for Medicare Advantage plans, whether they are in the plan’s network.
- Make a medication list. Include each prescription’s name, dosage, and how often you take it. Check coverage and pharmacy options.
- Think about how you use care. Consider routine appointments, specialists, and the possibility of needing more care in a given year.
- Compare total costs. Look beyond a monthly premium. Consider cost-sharing when you receive care, prescription expenses, and the costs of any separate coverage you need.
- Consider flexibility and plan rules. Decide how important provider choice, networks, referrals, and prior authorization are to you.
- Review your enrollment timing. Your ability to enroll in a plan and your right to buy Medigap are governed by different rules.
There isn’t one answer that fits everyone. A useful comparison is the one based on the providers and prescriptions you actually use, and the costs and rules you can manage.
Enrollment windows matter
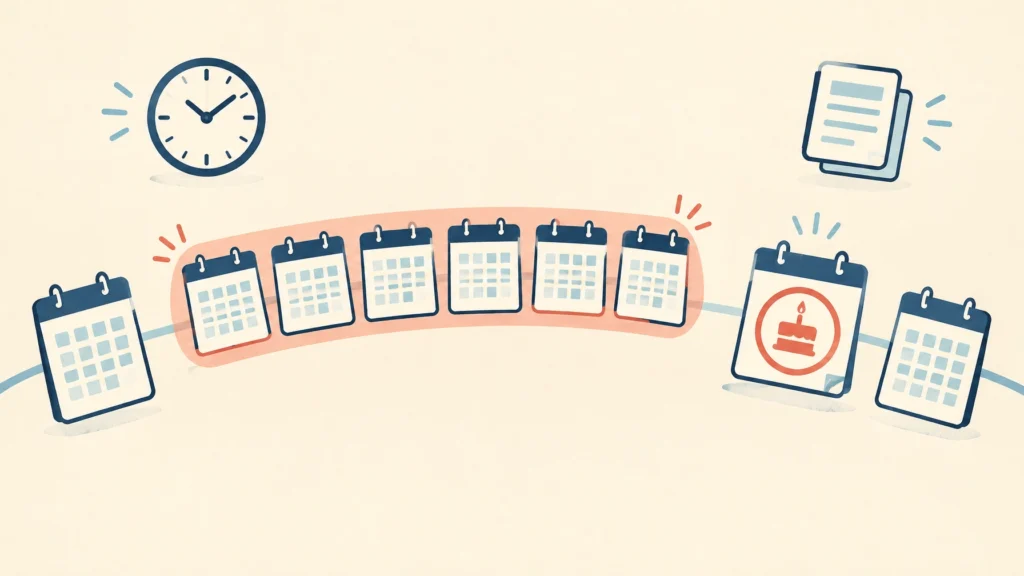
Most people first become eligible for Medicare at age 65. The Initial Enrollment Period for Medicare Parts A and B lasts seven months: it begins three months before the month you turn 65 and ends three months after your birthday month. If you’re working past 65 and have employer coverage, your situation may be different. Check with your employer and Social Security before delaying Part B. The Social Security Administration explains Medicare enrollment timing.
The annual Medicare Open Enrollment Period runs from October 15 through December 7. During this period, people can make certain changes to Medicare Advantage and Part D coverage. It is not a yearly federal Medigap Open Enrollment Period, and it does not automatically guarantee that you can buy a Medigap policy without medical underwriting.
If you’re already enrolled in Medicare Advantage, the Medicare Advantage Open Enrollment Period runs from January 1 through March 31. During this period, you may generally make one change: switch to another Medicare Advantage plan or return to Original Medicare. This is not a general Medigap enrollment period.
The one-time Medigap Open Enrollment Period
Your federal Medigap Open Enrollment Period lasts six months. It starts the first month you are both at least 65 and enrolled in Medicare Part B. During this period, you generally have the right to buy a Medigap policy without being denied or charged more because of a pre-existing health condition.
This period happens once; it does not repeat each year. After it ends, you may have fewer options unless you qualify for another guaranteed-issue right or state protection. Read more about when you can buy a Medigap policy on Medicare.gov.
Oklahoma’s Medigap Birthday Rule
Oklahoma has an additional state protection for eligible Medicare Supplement policyholders. Under the Oklahoma Insurance Department’s guidance, an eligible person with a Medicare Supplement policy may apply during an annual 60-day period beginning on their birthday to switch to a policy with equal or lesser benefits, without medical underwriting or pre-existing-condition exclusions. The birthday is day one of the period. The protection generally requires that there has not been a coverage gap greater than 90 days.
The Birthday Rule applies to Medicare Supplement coverage, not Medicare Advantage, and does not allow an upgrade to greater benefits without underwriting. It also does not guarantee a lower premium. For current details, review the Oklahoma Insurance Department’s Medicare Supplement FAQs.
Questions to ask before deciding
Before you enroll or change coverage, ask yourself:
- Are my preferred doctors, specialists, and hospitals accessible under this option?
- How are my prescriptions covered, and which pharmacies can I use?
- What would I pay in a year with few medical needs, and in a year with more care?
- Do I understand the rules for changing coverage later?
- If I’m considering Medigap, am I within my six-month federal Open Enrollment Period or eligible for another protection?
If you’re turning 65, our Turning 65 Medicare Checklist can help you organize key dates and questions. You can also explore our Medicare FAQs and Medicare in a Nutshell for more plain-English explanations.
Take your time
Choosing between Medicare Advantage and Medicare Supplement coverage means weighing how you want to receive care, how you use prescription coverage, what providers you want to see, and how costs and plan rules fit your circumstances. If you’d like help understanding the differences, a conversation can be a way to review your questions, without pressure to make a particular choice.
Sansone Advisory Group is an independent insurance agency serving clients across Oklahoma, including Tulsa and the surrounding communities. We do not offer every plan available in your area. Currently we represent between 1 and 7 organizations which offer between 3 and 58 products in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
Sansone Advisory Group is not connected with or endorsed by the U.S. government or the federal Medicare program. This article is for general educational purposes and is not a personalized determination of eligibility, coverage, or enrollment rights. Verify current rules with Medicare.gov, Social Security, or the Oklahoma Insurance Department.
Leave a Reply